Before signing a mortgage, auto loan, or education loan, you need to know more than just the initial monthly installment: you need to know how much cumulative interest you will pay over the full term, how sensitive your payment is to a $+0.5%\text{–}1.0%$ rate hike, and how partial prepayments alter your schedule.
Under equal-payment amortization (fixed total monthly installment), the monthly payment $A$ for principal $P$, monthly interest rate $r = r_{\text{annual}} / 12$, and total monthly payments $n = 12Y$ is:
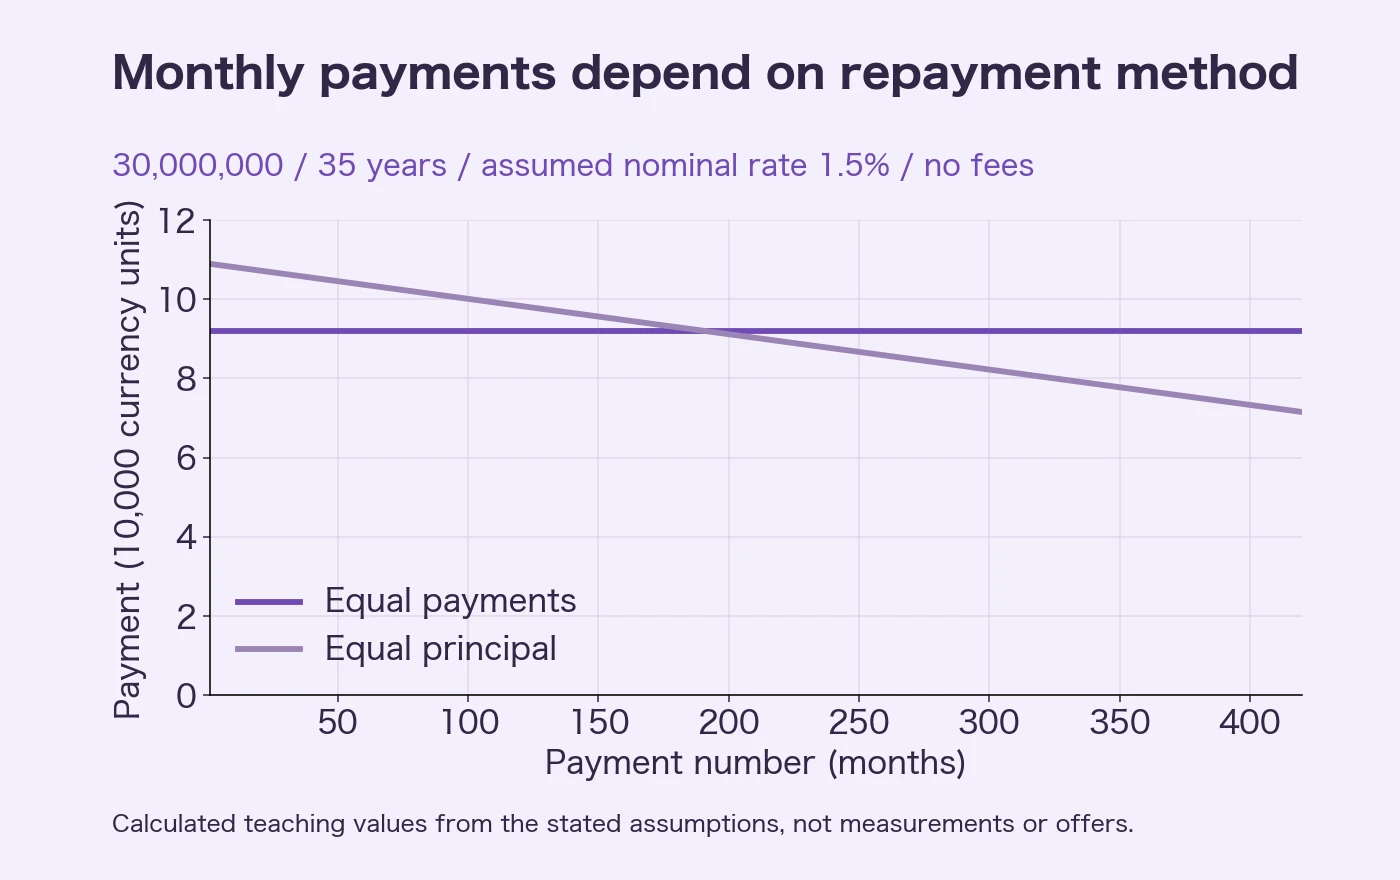
For example, borrowing 30,000,000 over 35 years (420 payments) at an assumed 1.5% annual rate ($r = 0.00125$) produces a constant monthly payment of ~91,855 and ~8,579,239 in total interest. Under equal-principal amortization, the first payment is ~108,929, the final payment is ~71,518, and total interest drops to 7,893,750—saving ~685,489.
This guide walks through the exact formulas, a 30M / 40M / 50M × interest-rate matrix, a quantitative comparison of term-reduction vs. payment-reduction prepayments, and a pre-contract safety checklist.
4-Step Decision Framework for Loan Amortization
Evaluate any loan offer in four structured steps to avoid unit mismatches and cash-flow strain:
Convert nominal annual rate $R$ to monthly rate $r = R \div 12$ and years $Y$ to total monthly payments $n = 12Y$ (e.g., 1.5% over 35 years $\rightarrow r = 0.00125, n = 420$).
→ Prevents 12× rate-entry errorsSelect equal payments to keep early monthly bills lower and predictable, or equal principal if you have ample initial income and want minimum lifetime interest.
→ 685,489 interest gap on 30M at 1.5%For variable or adjustable-rate loans, test whether your household budget still works if the rate rises by $+0.5\%$ to $+1.0\%$.
→ Keep payments ≤ 25% of net take-home payCompare risk-free interest saved via term-shortening prepayments against tax-advantaged investing and mortgage tax credits.
→ Term reduction saves ~1.94× more interestEqual-Payment vs. Equal-Principal Formulas and Comparison Table
As outlined by the Japanese Bankers Association (JBA) and the CFPB, standard amortizing loans follow one of two structures:
1. Equal-Payment Amortization (Annuity Method)
Every monthly bill $A$ is constant. Early in the loan, interest consumes a larger share of $A$; over time, the principal reduction accelerates exponentially.
- When monthly rate $r > 0$:
- When interest rate is zero ($r = 0$): Because the standard denominator becomes $0$, compute $A = P \div n$ directly.
2. Equal-Principal Amortization (Linear Principal Reduction)
Each month repays a fixed slice of principal $p = P \div n$, plus interest on the remaining balance.
- Payment in month $k$ ($k = 1, 2, \dots, n$):
- Total Interest $I_{\text{total}}$ (Arithmetic Series Sum): (See our Arithmetic and Geometric Sequences Guide for the series derivation.)
Worked Comparison: 30,000,000 over 35 Years (420 Months) at 1.5% ($r = 0.00125$)
| Metric | Equal Payments (Annuity) | Equal Principal (Linear) | Key Difference & Decision Rule |
|---|---|---|---|
| Monthly Formula | $A = P \cdot r \div {1-(1+r)^{-n}}$ | $A_k = \frac{P}{n} + \text{Balance}\times r$ | Geometric annuity vs. arithmetic decline |
| Month 1 Payment | ~91,855 (Principal 54,355 + Interest 37,500) | ~108,929 (Principal 71,429 + Interest 37,500) | Equal principal starts +17,074/month higher |
| Year 10 (Month 121) Payment | ~91,855 (Principal 63,182 + Interest 28,673) | ~98,214 (Principal 71,429 + Interest 26,786) | Crossover occurs around Month 167 (~13 yrs 11 mos) |
| Final (Month 420) Payment | ~91,855 | ~71,518 (Principal 71,429 + Interest 89) | Equal principal eases burden in later years |
| Cumulative Interest | ~8,579,239 | 7,893,750 | Equal principal saves ~685,489 in interest |
| Total Repaid | ~38,579,239 | 37,893,750 | Calculated from unrounded monthly figures |
| Best Suited For | Households prioritizing stable initial cash flow & reserves | Borrowers with strong current income minimizing total cost | Equal payments + periodic prepayments achieves a similar result |
- 💡 Load directly in the calculator: Open 30,000,000 at 1.5% for 35 years in the Loan Repayment Calculator
35-Year Rate Sensitivity Matrix: 30M, 40M & 50M Principals (0.5%–2.5%)
How much does a $+0.5%$ rate difference change your monthly payment and lifetime interest? The table below compares 35-year (420-month) equal-payment loans across three principal sizes.
| Assumed Annual Rate | 30,000,000: Monthly (Total Interest) | 40,000,000: Monthly (Total Interest) | 50,000,000: Monthly (Total Interest) | Impact of Each +0.5% Rate Increase |
|---|---|---|---|---|
| 0.5% p.a. | 77,876 (Interest: 2.71M) | 103,834 (Interest: 3.61M) | 129,793 (Interest: 4.51M) | Baseline ultra-low rate scenario |
| 1.0% p.a. | 84,686 (Interest: 5.57M) | 112,914 (Interest: 7.42M) | 141,143 (Interest: 9.28M) | On 30M: +6,810/mo & +2.86M interest |
| 1.5% p.a. | 91,855 (Interest: 8.58M) | 122,474 (Interest: 11.44M) | 153,092 (Interest: 14.30M) | On 30M: +7,169/mo & +3.01M interest |
| 2.0% p.a. | 99,379 (Interest: 11.74M) | 132,505 (Interest: 15.65M) | 165,631 (Interest: 19.57M) | On 30M: +7,524/mo & +3.16M interest |
| 2.5% p.a. | 107,249 (Interest: 15.04M) | 142,998 (Interest: 20.06M) | 178,748 (Interest: 25.07M) | On 30M: +7,870/mo & +3.31M interest |
- 💡 Load directly in the calculator:
Key Takeaway: Over a 35-year horizon, each $0.5%$ increase in the annual interest rate adds roughly 2.86M to 3.31M in cumulative interest per 30M borrowed. On a 40M loan, moving from $1.0%$ to $2.0%$ raises the monthly bill from $112,914$ to $132,505$ ($+19,591/\text{month}$) and more than doubles total interest from 7.42M to 15.65M.
Interactive Amortization Schedule
Test Your Exact Principal, Interest Rate, and Repayment Term
Enter any loan amount, annual interest rate, and years/months to instantly view your monthly payment, cumulative interest, and year-by-year remaining balance table.
Prepayment Comparison: Term Reduction vs. Payment Reduction
Making a lump-sum partial prepayment directly reduces your outstanding principal. As detailed in the JBA Prepayment Guide, you can apply that principal reduction in two ways.
Scenario: Borrowing 30,000,000 over 35 years at 1.5% (monthly payment ~91,855). After 5 years (60 payments, remaining balance 26,389,036), you make a ~1,000,000 lump-sum prepayment:
| Comparison Metric | Term Reduction (Keep Monthly Payment) | Payment Reduction (Keep Remaining Term) | Decision Rule |
|---|---|---|---|
| New Monthly Payment | ~91,855 (unchanged) | ~88,374 (reduced by −3,481/month) | Choose payment reduction for immediate monthly relief |
| Remaining Term | 344 months (shortened by 16 months) | 360 months (remains 30 years) | Choose term reduction to finish before retirement |
| Total Interest Saved | ~491,833 saved | ~253,353 saved | Term reduction saves ~1.94× more interest |
| Best Scenario | Maximizing lifetime savings & paying off debt earlier | Lowering fixed monthly obligations ahead of tuition/income changes | Default to term reduction if monthly cash flow is stable |
To compare paying down a low-rate loan early versus investing surplus cash in a compound savings account, see our Compound Interest Formula & Savings Guide and Compound Interest Calculator. Remember that loan prepayment delivers a guaranteed, tax-free return equal to your loan interest rate, whereas market investments carry volatility risk.
Pre-Contract Checklist: Debt-to-Income Ratio & Hidden Costs
- Keep Debt-to-Income (DTI) Within 20% of Gross Income (≤25% of Net Income) Although underwriting guidelines (such as Flat 35) permit total annual repayments up to 30%–35% of gross income, borrowing at the 35% ceiling can consume over 40% of take-home pay. Aim for ≤20% of gross income (≤25% of net take-home pay) (see our Percentage Calculation Guide).
- Account for Closing Costs, Taxes, and Maintenance Origination fees (often 2.2% tax-included in Japan; see the Tax Calculation Guide), guarantee fees, registration taxes, and insurance typically add 5%–8% of the property price upfront, plus ongoing property taxes and HOA/condo reserve fees.
- Verify Variable-Rate Cap Rules and Unpaid Interest Risks Not all variable-rate loans include 5-year payment resets or 125% payment caps. Even where caps exist, rising rates shift more of each payment toward interest, slowing principal payoff and potentially creating unpaid interest if rates spike sharply.
- Preserve 6–12 Months of Emergency Living Expenses Never drain your entire cash reserve for a down payment or prepayment. Maintain 6–12 months of core living expenses in liquid savings.
Verification Scope
All formulas, comparison tables, and prepayment figures in this guide were verified on October 27, 2026 against official JBA and JHF documentation using double-precision arithmetic. The Loan Repayment Calculator models equal-payment amortization up to 600 months and excludes closing fees, bonus payments, and mid-term rate changes. Explore more financial and everyday calculators in the Utility Category.
FAQ
Should I choose equal-payment (annuity) or equal-principal repayment?
Choose equal-payment repayment if keeping initial monthly cash flow predictable is your priority (e.g., balancing childcare, education, or emergency savings). Choose equal-principal repayment if your household income can comfortably absorb a higher initial installment in exchange for faster principal reduction and lower lifetime interest. On a 30,000,000 loan over 35 years at 1.5%, equal principal saves ~685,489 in total interest but starts ~17,074 per month higher.
Which prepayment option saves more interest: term reduction or payment reduction?
Term reduction saves substantially more total interest. On a 30,000,000 loan at 1.5% over 35 years, making a ~1,000,000 prepayment after 5 years (60 months) under term reduction shortens the remaining schedule by 16 months (1 year 4 months) and saves ~491,833 in interest. Under payment reduction, the monthly bill drops by ~3,481 over the remaining 30 years, but total interest saved is ~253,353.
What is the monthly payment and total interest for 10,000,000 at 1.2% over 10 years?
With monthly rate r = 0.012 / 12 = 0.001 and n = 120 monthly payments, the unrounded equal monthly payment is 88,474.92 (~88,475 rounded), total repayment is ~10,616,990, and total interest is ~616,990. Do not multiply the rounded monthly display figure by 120 to compute total interest.
Do variable-rate payment caps (5-year / 125% rules) protect me from interest rate increases?
They smooth monthly cash-flow shocks but do not forgive accrued interest. When rates rise under a capped payment, the interest share of each installment expands while the principal share shrinks. If rates jump sharply enough that monthly interest exceeds the capped payment, unpaid interest accumulates and must be settled later. Moreover, not all lenders offer 5-year or 125% rules.
What is a safe debt-to-income (DTI) ratio for a mortgage?
While underwriting caps (such as Flat 35 in Japan) often allow total annual debt service up to 30%–35% of gross annual income, a practical household safety benchmark is keeping loan payments at or below 20% of gross income (or 25% of net take-home pay), leaving room for property taxes, insurance, maintenance fees, and emergency reserves.