Compound interest applies each period’s interest not only to your original principal $P$, but also to all previously accumulated interest. For a constant annual rate $r$ (enter $5%$ as $0.05$) compounded once per year over $n$ years, the balance is $A = P(1+r)^n$.
When comparing financial calculators or planning long-term savings, even small differences in compounding frequency ($k=1$ vs. $k=12$), contribution timing (month-end vs. month-start), or fees and taxes can shift 20- to 30-year projections by tens of percents. You can test your own principal, monthly contribution, and rate immediately in the Compound Interest Calculator above.
Decision Framework: 4 Compounding Models & When to Use Each
Annual compounding uses P(1+r)ⁿ; monthly compounding divides nominal rate $r$ by 12 and compounds $12n$ times: P(1+r/12)^(12n). At 5% nominal rate, monthly compounding produces an effective annual rate (EAR) of 5.116%.
With monthly rate $i = r/12$ and $m = 12n$ months, month-end deposits accumulate to C × {(1+i)^m − 1} / i. Month-start deposits multiply that sum by (1+i). Our calculator uses month-end timing.
Use 72 / Rate(%) for quick mental estimates, and n = ln(2) / ln(1+r) (verifiable in the Logarithm Calculator) for exact reports.
Subtract annual fund expense ratios from $r$ before simulating, account for capital gains taxes (e.g., 20.315% in Japan outside NISA), and compare against high-interest debt in the Loan Repayment Calculator.
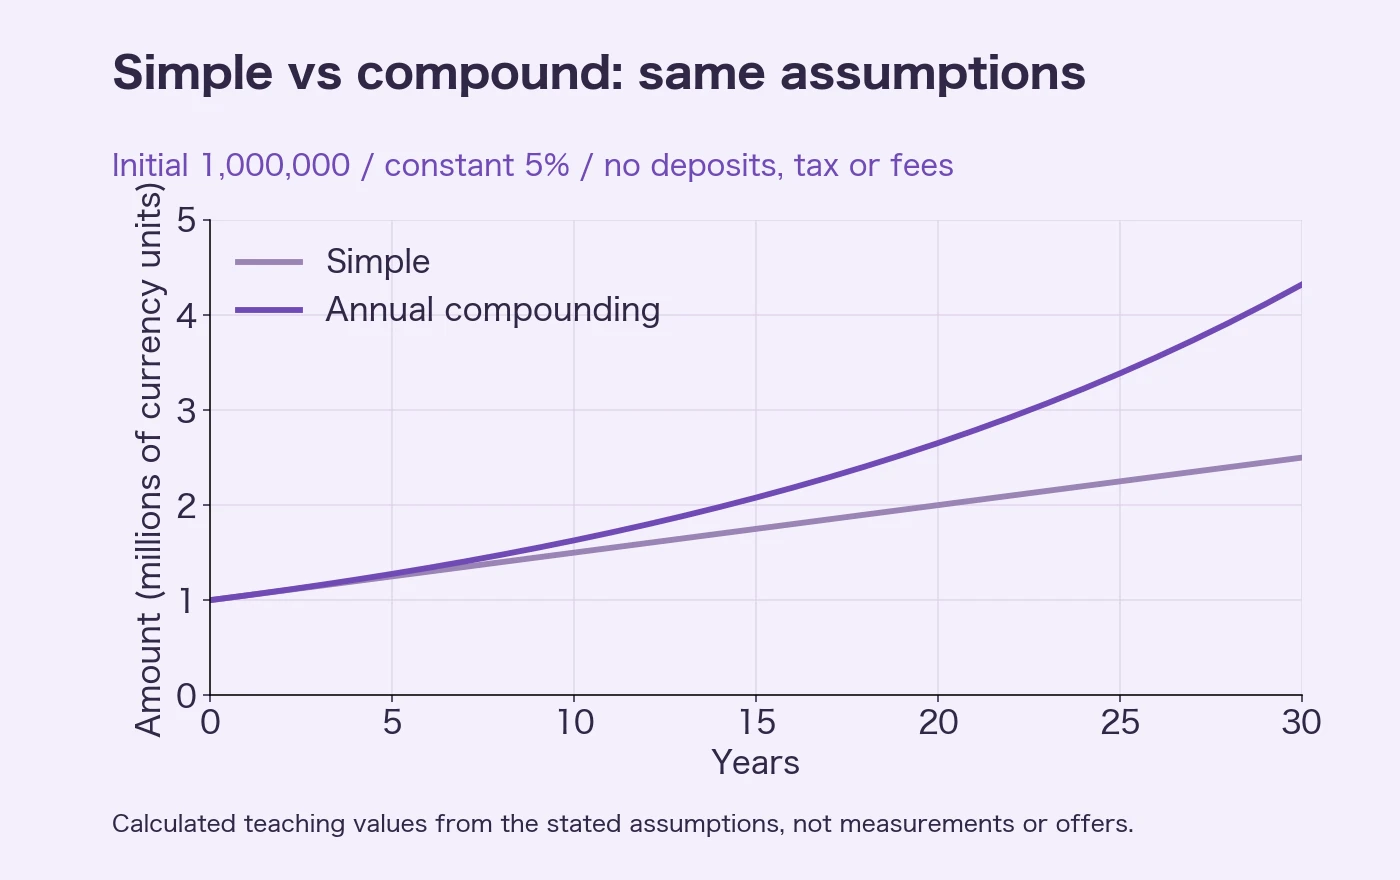
Table 1: Simple vs. Annual vs. Monthly Compounding Over 30 Years (Principal 1,000,000 at 5%)
Assuming initial principal $P = 1,000,000$, constant nominal annual rate $r = 5.0%$ ($0.05$), no additional deposits, and no taxes or fees:
- Simple Interest: $A_{\text{simple}} = P(1 + r n) = 1,000,000 \times (1 + 0.05n)$
- Annual Compounding ($k=1$): $A_{\text{annual}} = P(1 + r)^n = 1,000,000 \times (1.05)^n$
- Monthly Compounding ($k=12$, Tool Method): $A_{\text{monthly}} = P(1 + 0.05/12)^{12n}$
| Years ($n$) | Simple Interest | Annual Compounding ($k=1$) | Monthly Compounding ($k=12$, Tool) | Monthly Compound vs. Simple Difference |
|---|---|---|---|---|
| 0 yrs | 1,000,000 | 1,000,000 | 1,000,000 | +0 |
| 5 yrs | 1,250,000 | 1,276,282 | 1,283,359 | +33,359 |
| 10 yrs | 1,500,000 | 1,628,895 | 1,647,009 | +147,009 |
| 15 yrs | 1,750,000 | 2,078,928 | 2,113,704 | +363,704 |
| 20 yrs | 2,000,000 | 2,653,298 | 2,712,640 | +712,640 |
| 30 yrs | 2,500,000 | 4,321,942 | 4,467,744 | +1,967,744 |
👉 Load Principal 1,000,000 at 5% for 10 Years in the Compound Interest Calculator
Nominal Annual Rate (APR) vs. Effective Annual Rate (EAR)
When a nominal annual rate $r$ is compounded $k$ times per year, the Effective Annual Rate ($\text{EAR}$) is (see our Exponent Calculator):
At nominal $r = 5.0%$, semiannual compounding ($k=2$) yields $\text{EAR} = 5.0625%$, and monthly compounding ($k=12$) yields $\text{EAR} = (1 + 0.05/12)^{12} - 1 \approx \mathbf{5.1162%}$.
Table 2: 20-Year Monthly Contribution Matrix (Monthly Savings vs. Nominal Rate)
Starting from $P = 0$ and depositing $C$ at the end of each month for $m = 240$ months (20 years) at monthly rate $i = r/12$, the future value formula (derived from geometric series; see the Sequence Calculator) is:
| Monthly Deposit $C$ | 20-Year Total Principal | Final Balance at 3.0% (Gain) | Final Balance at 5.0% (Gain) | Final Balance at 7.0% (Gain) |
|---|---|---|---|---|
| 10,000 / mo | 2,400,000 | 3,283,020 (+883,020) |
4,110,337 (+1,710,337) |
5,209,267 (+2,809,267) |
| 30,000 / mo | 7,200,000 | 9,849,060 (+2,649,060) |
12,331,010 (+5,131,010) |
15,627,800 (+8,427,800) |
| 50,000 / mo | 12,000,000 | 16,415,100 (+4,415,100) |
20,551,683 (+8,551,683) |
26,046,333 (+14,046,333) |
| 100,000 / mo | 24,000,000 | 32,830,200 (+8,830,200) |
41,103,367 (+17,103,367) |
52,092,666 (+28,092,666) |
- At 10,000/month, 6% nominal annual rate ($i = 0.005$), 20 years ($m = 240$), the balance reaches $4,620,409$ ($2,400,000$ principal + $2,220,409$ compound gain).
- At 30,000/month, 4% nominal annual rate, 20 years, the balance reaches $11,003,239$ ($7,200,000$ principal + $3,803,239$ gain). 👉 Load 30,000/month at 4% for 20 Years in the Compound Interest Calculator
Table 3: Rule of 72 vs. Exact Logarithmic Doubling Time ($\ln 2 / \ln(1+r)$)
| Annual Rate $R$ (%) | Rule of 72 ($72 \div R$) | Exact Annual Compounding $\ln 2 / \ln(1+r)$ | Exact Monthly Compounding $\ln 2 / {12\ln(1+r/12)}$ | Rule of 72 Error (vs. Annual) |
|---|---|---|---|---|
| 1.0 % | 72.00 yrs | 69.66 yrs | 69.34 yrs | +2.34 yrs |
| 3.0 % | 24.00 yrs | 23.45 yrs | 23.13 yrs | +0.55 yrs |
| 5.0 % | 14.40 yrs | 14.21 yrs | 13.89 yrs | +0.19 yrs |
| 6.0 % | 12.00 yrs | 11.90 yrs | 11.58 yrs | +0.10 yrs |
| 8.0 % | 9.00 yrs | 9.01 yrs | 8.69 yrs | −0.01 yrs (nearly exact) |
| 10.0 % | 7.20 yrs | 7.27 yrs | 6.96 yrs | −0.07 yrs |
👉 Load Rule of 72 Example (1,000,000 at 6% for 12 Years) in the Calculator
Real-World Checklist: Taxes, Fees, Inflation & Debt Amortization
As emphasized in FSA educational guides and the SEC Compound Interest Calculator, a constant-rate formula is a mathematical projection, not a guaranteed return. Before making financial decisions, check four factors:
- Tax-Advantaged vs. Taxable Accounts: In Japan, capital gains and dividends in taxable accounts are subject to 20.315% withholding tax, whereas investments within the revised NISA framework (up to 1.2M JPY/year in the periodic investment quota, 2.4M JPY/year in the growth quota, and 18M JPY lifetime principal cap) compound tax-free.
- Annual Expense Ratios: Deduct fund management fees from your assumed gross return (e.g., 5.0% gross minus 0.5% fee = 4.5% net input rate).
- Inflation & Purchasing Power: Adjust nominal growth for expected inflation $\pi$ using the Fisher relation $r_{\text{real}} = (1 + r_{\text{nominal}})/(1 + \pi) - 1$.
- High-Interest Debt Works in Reverse: Credit-card revolving balances and loans compound against you. Compare debt payoff schedules using the Loan Repayment Calculator and our Loan Repayment Guide.
What Was Checked
On October 27, 2026, we verified the 30-year simple vs. annual vs. monthly compounding table, the 20-year monthly contribution matrix, the Rule of 72 vs. exact natural-logarithm comparison table, and tax/fee boundary notes.
FAQ
How much difference does monthly vs. annual compounding make at 5% over 30 years?
For an initial principal of 1,000,000 at a 5% nominal annual rate over 30 years with no extra contributions or fees, annual compounding yields 1,000,000 × (1.05)³⁰ ≈ 4,321,942. Monthly compounding (monthly rate 0.05/12 ≈ 0.4167%, effective annual rate EAR ≈ 5.116%) yields 1,000,000 × (1 + 0.05/12)³⁶⁰ ≈ 4,467,744—an extra 145,802 purely from compounding frequency.
Why do beginning-of-month and end-of-month contributions give different totals?
When you deposit at the beginning of each month (annuity due), every payment earns one additional month of interest compared with month-end deposits (ordinary annuity). Specifically, FV_begin = FV_end × (1 + i), where i = r/12. Our calculator uses month-end deposits.
How accurate is the Rule of 72 compared with the exact logarithmic formula?
For annual compounding, exact doubling time is n = ln(2) / ln(1 + r). Because ln(2) ≈ 0.6931, '69.3 / Rate(%)' is closer at very low rates (1–2%), whereas '72 / Rate(%)' incorporates second-order curvature and is most accurate around 6%–10% annual return (within 0.1 years). It cannot be applied to zero or negative interest rates.
How do investment taxes and expense ratios affect compound growth?
Ongoing management fees (expense ratios) directly reduce the net annual compounding rate r. For example, a 1.2% annual fee on a 5.0% gross return leaves a 3.8% net compounding rate. Furthermore, in taxable accounts (such as Japan's 20.315% withholding tax on realized gains and dividends), tax drag reduces reinvested or final net proceeds compared with tax-advantaged accounts like NISA or IRAs.
How do I separate total investment gains from my own contributions?
Subtract total principal contributed (Initial Principal P + Monthly Contribution C × Total Months m) from the final balance A. For example, if you start with 0 and contribute 30,000 per month for 20 years (240 months) at 4% nominal annual rate, total principal contributed is 7,200,000 and the final balance is 11,003,239, so net compound gain is 3,803,239.